



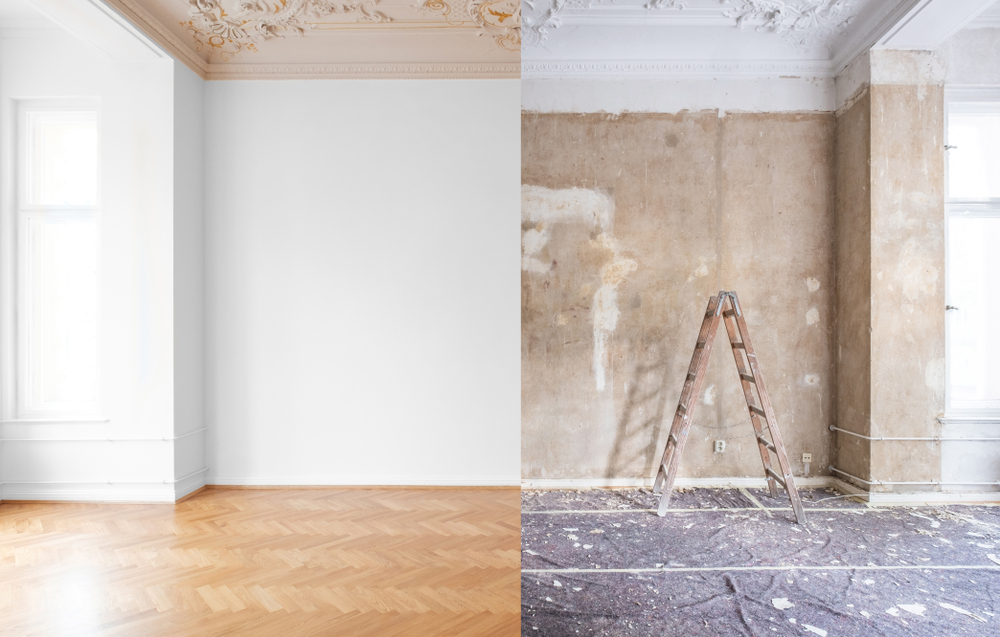
When comparing a new-build with a doer-upper, focus on what each property needs before you can let it. A doer-upper needs work, from fresh paint to major repairs, while an older home may need very little. A new-build can be complete or still being built, which also affects your budget and timing.
New-build vs doer-upper at a glance
Factor
New-build
Doer-upper
Condition
Check finish, fittings and defects.
Survey the home and work needed.
Upfront works
Fitting out may still be needed.
Budget for repairs and improvements.
Maintenance
Allow for upkeep; check warranty limits.
Assess repairs and items needing replacement.
Energy use
Check the EPC and heating.
Assess the EPC and suitable upgrades.
Time to let
Build and setup dates matter.
Works and checks may delay letting.
Tenant appeal
Review layout and included fittings.
Plan a useful, durable finish.
Mortgage
Check new-build terms and incentives.
Check current condition and lender requirements.
Compare the full upfront property costs
A lower price can still mean finding more cash before letting. Alongside your deposit, allow for purchase tax, fees and any work needed. You can build a fuller budget by reviewing the costs of buying and running a buy-to-let.
This example assumes a 75% mortgage on each purchase, with lender values matching the prices. It assumes both homes qualify for the loan and you pay for works from cash.
Illustration
Completed new-build
Home needing work
Price
£250,000
£220,000
25% deposit
£62,500
£55,000
Works or fitting out
£2,000
£25,000
Deposit plus stated works only
£64,500
£80,000
These subtotals cover the deposit and stated works only. Your full budget also needs purchase tax, legal, survey and lender fees, plus costs paid before rent starts. You will need cash for unexpected work and an ongoing reserve too. Actual loan terms and values may differ, and works may not add their cost to the home’s value.
For a new-build, the price may not include flooring, blinds or white goods, so check what comes with the property rather than relying on the show home.
Allow for refurbishment costs and delays
TIMING AND CASH
A survey can help you scope the work before seeking itemised quotes. Agree when trades can start and set aside money for unexpected work, based on the survey findings.
While work continues, mortgage payments, insurance and other costs may still fall due. Buying off-plan brings a separate risk: the home may not be finished on time. Allow for delays before relying on rental income.
Think about energy efficiency and maintenance
Compare the actual Energy Performance Certificate (EPC), heating and insulation to see how energy efficient each home is. Suitable improvements can form part of your works budget, alongside preparing for the planned EPC changes in England and Wales. If tenants pay energy bills, direct bill savings benefit them.
A new-build warranty has limits, so check what it covers, the deadlines and exclusions. It does not cover every defect or replace routine upkeep.
Consider what local tenants actually need
The rental market around the property matters as much as its age. Ask a letting agent for evidence from similar homes, including rents and how long they take to let. Matching the property to local tenant demand means weighing layout, storage, transport links and competing homes. Neither route guarantees more rent.
Check how lenders view the property
New-build buy-to-let mortgage rules can differ for houses and flats. Tell the lender about builder incentives and check that it accepts the warranty. The lender’s valuation checks the home as security for the loan; it does not replace a survey. If the lender values the home below the price, you may need more cash to bridge the gap.
A doer-upper needing major work may need a different funding route, with its own costs and repayment plan. Check how lenders assess a buy-to-let application before committing. Do not assume you can recover the cost of the work through a later remortgage.
How Muttuo can help
Muttuo can help you review mortgage options for the property and work you plan. We will explain borrowing costs and lender requirements so you can prepare your budget.
Review the planned borrowing
Compare rates, fees and payments
Check the lender’s requirements



Plan your next property purchase
Talk through the borrowing with an adviser.

Your home may be repossessed if you do not keep up repayments on your mortgage.
The FCA does not regulate some buy-to-let mortgages.


