







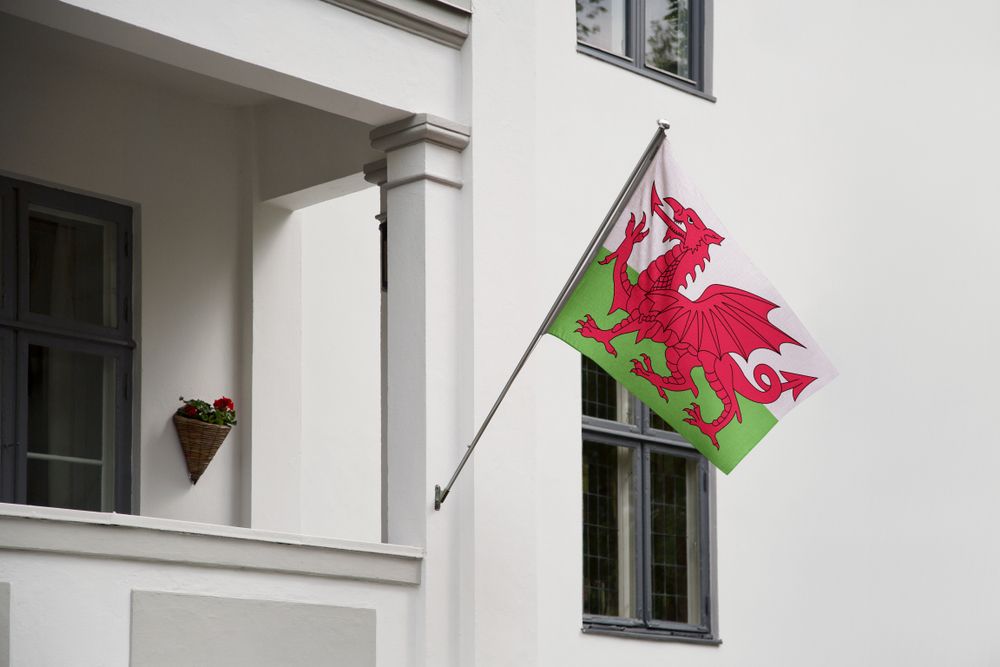
What is a Help to Buy equity loan?
Help to Buy Wales provides a government equity loan towards an eligible new-build home. It is a separate loan secured against your property, alongside your lender mortgage.
Unlike a standard repayment mortgage, the amount you repay is linked to your home’s value. If you borrow 20% of the purchase price, you generally repay 20% of its value when you clear the loan. This means the amount can rise or fall as your home’s value changes.
How Help to Buy Wales works
WHO
First-time buyers and home movers
You may qualify when buying your first home or moving, provided you need the support and meet the scheme’s checks.
HOMES
New-build homes from registered builders
The scheme covers eligible new homes in Wales. The builder must be registered with Help to Buy Wales.
SUPPORT
Three parts fund your purchase
Your cash deposit, lender mortgage and government equity loan work together to cover the purchase price.
REPAY
Your home’s value affects repayment
You repay the government’s percentage share, so the amount can rise or fall as your home’s value changes.
Who can apply for the scheme?
The property
A Welsh new build costing up to £300,000, bought from a builder registered with the scheme, with an EPC rating of B or better.
Your circumstances
It must be your only home. You must meet the scheme’s eligibility requirements and pass both scheme and lender checks. You cannot keep another home or normally let out the whole property.
Your deposit and mortgage explained
The Help to Buy scheme in Wales requires at least a 5% cash deposit. The equity loan covers up to 20% of the purchase price, while a repayment mortgage from a qualifying lender funds the rest. Your mortgage payments cover both the amount borrowed and interest.
Illustrative example: a £240,000 home
Funding
Amount
Share
Your deposit
£12,000
5%
Government loan
£48,000
20%
Lender mortgage
£180,000
75%
This example is not a mortgage offer. Alongside your deposit, you also need to budget for legal and mortgage fees, any Land Transaction Tax due, and the costs of owning your home.
What the equity loan will cost
The equity loan is interest-free for the first five years, although a £1 monthly management fee applies from the start.
From year six, interest starts at 1.75% a year on the equity loan amount, payable monthly. The rate then increases annually using CPI inflation plus 2%, with negative CPI treated as zero. This increases the existing rate proportionately; it does not add two percentage points.
These payments cover interest and fees only. They do not reduce your equity loan.
How you repay the equity loan
Your repayment is linked to your home’s value when you repay, rather than simply the amount originally borrowed. If your property rises in value, the amount you owe can rise too.
For example, an outstanding 20% equity loan would mean repaying £54,000 if the relevant property value were £270,000. When selling, repayment is generally based on the higher of the sale price or an independent RICS valuation.
The loan normally becomes repayable after 25 years, or sooner if you sell your home or repay your main mortgage. You can also repay it earlier, either fully or through qualifying partial repayments.
Weighing up the benefits and downsides
Potential benefits
A smaller deposit
You can apply with a deposit of at least 5%, subject to eligibility and affordability checks.
A smaller lender mortgage
The equity loan can cover up to 20% of the purchase price, reducing the mortgage you need.
Interest-free for five years
This can help with initial costs, although the £1 monthly management fee still applies.
Possible drawbacks
Repayment can grow
If your home increases in value, the amount needed to repay the equity loan can rise.
Costs increase after five years
Interest starts in year six, alongside the monthly management fee.
Less flexibility later
Remortgaging, letting and some property changes require permission under the scheme.
How to apply for the scheme
First, discuss funding with an adviser. Then reserve a home, appoint a scheme-trained conveyancer and apply for the equity loan. Make your full lender mortgage application after the scheme issues its Authority to Proceed.
How Muttuo can help
We can help you understand the scheme’s costs, review your deposit and compare suitable lender mortgages
Review your deposit
Budget for future charges
Compare lender mortgages

Plan your Welsh home purchase
Discuss your Help to Buy Wales mortgage funding options.

Your home may be repossessed if you do not keep up repayments on your mortgage.
Common Help to Buy Wales questions
When do applications close?
The current deadline is 31 March 2027. This is the application deadline, rather than the date every purchase must complete.
Can I buy an older home?
No. Only eligible new builds from registered builders qualify.