



Buying your first home can feel exciting, but it can also feel confusing at first. There are new terms to understand, costs to plan for and lender checks to pass before you can get a mortgage.
A first-time buyer mortgage is the mortgage you use to buy your first home. In most cases, it is not a special product on its own. It usually means applying for a residential mortgage as someone who has not owned a property before.
Being a first-time buyer can still affect your options. You may be buying with a smaller deposit, using family support, applying with another person or checking whether a buying scheme could help.
This guide explains how first-time buyer mortgages work, what lenders look at, how much deposit you may need and what costs to think about before you apply.
First-time buyer mortgages in simple terms
- A first-time buyer mortgage helps you buy your first home using a mortgage and a deposit.
- Lenders check your income, spending, debts, credit profile, deposit and the property.
- Your deposit size affects your loan-to-value, which can influence rates and lender choice.
- An Agreement in Principle can give you an early borrowing estimate before you make an offer.
- The right mortgage depends on affordability, lender criteria, property type and your future plans.
What is a first-time buyer mortgage?
A first-time buyer mortgage is a residential mortgage for someone buying their first home.
It is not always a separate product. Many first-time buyers choose from standard mortgage options, such as fixed-rate mortgages, repayment mortgages, 5% deposit mortgages or new build mortgages, depending on their circumstances.
What makes the application different is your position as a buyer. You may be dealing with affordability checks, deposit evidence, stamp duty, solicitor checks and property decisions for the first time.
Lenders will still assess whether the mortgage looks affordable and whether the property is suitable security for the loan. This means your income, spending, deposit, credit profile and property choice all matter.
The aim is to find a mortgage that fits your budget now and still makes sense for the first few years of owning your home.
Who counts as a first-time buyer?
A first-time buyer is usually someone buying a property who has not owned a home before.
This can sound simple, but the details matter. If you have previously owned a property, inherited a property or owned a home outside the UK, you may not always be treated as a first-time buyer for mortgage, scheme or tax purposes.
If you are buying with someone else, their position can also matter. For example, one person may be buying for the first time while the other has owned before. This could affect which schemes, tax rules or lender options are available.
Different lenders, schemes and tax rules may define first-time buyer status in slightly different ways. Before relying on a first-time buyer benefit, it is worth checking how the rule applies to your situation.
The key point is to be clear about your ownership history before you apply. That way, you can avoid surprises later in the mortgage or legal process.
Getting your finances ready before applying
Before you apply for a first-time buyer mortgage, it helps to make sure your finances are clear and ready for lender checks.
Lenders will usually look at your income, spending, debts, credit profile and deposit source. Checking these areas early can help you spot anything that may affect your application.
Start by reviewing your credit report, bank statements and regular commitments. It is also worth avoiding unnecessary new credit in the months before applying, as new loans, credit cards or finance agreements can affect affordability.
If part of your deposit is being gifted by family, prepare the evidence early. Lenders and solicitors will usually need a clear paper trail showing where the money came from.
The aim is not to make your finances look perfect. It is to make them easy for a lender to understand.
How much can you borrow as a first-time buyer?
How much you can borrow depends on your income, spending, deposit, credit profile and the lender’s affordability checks.
As a broad guide, many lenders may start by looking at around 4 to 4.5 times your income. In some cases, higher income multiples may be available, sometimes above 6 times income, depending on your earnings, commitments, deposit size, credit profile and the lender’s criteria.
However, lenders do not look at income alone. They also review regular commitments such as loans, credit cards, childcare costs, car finance, dependants and household spending. These costs can reduce the amount you may be able to borrow.
Your employment type can also make a difference. Employed income, self-employed income, bonuses, overtime, commission and contract work may all be assessed differently.
This is why two buyers with the same income may be offered different borrowing amounts. A mortgage calculator can give you a useful starting point, but it cannot show every lender’s criteria. Before making an offer, it is worth checking what lenders may actually be prepared to approve.
Check what you could afford
Estimate your borrowing based on your income, then compare how the numbers could look alongside your deposit and monthly repayments.
How much deposit do first-time buyers need?
The deposit is the amount of money you put towards the property yourself. The mortgage covers the rest.
Some first-time buyers may be able to buy with a 5% deposit, which usually means borrowing the remaining 95% through the mortgage. This is known as a 95% loan-to-value mortgage, or 95% LTV.
What is loan-to-value?
Loan-to-value, often shortened to LTV, is the percentage of the property value you borrow through the mortgage. For example, if you buy with a 10% deposit, you usually have a 90% LTV mortgage.
A larger deposit can sometimes improve your mortgage options. For example, moving from a 5% deposit to a 10% deposit may give you access to more lenders, more products or different interest rates.
However, the right deposit size depends on your savings, property price, monthly budget and how quickly you want to buy. Waiting to save more may improve your options, but it may also delay your purchase.
You should also remember that your deposit is not the only upfront cost. Legal fees, survey costs, moving costs and stamp duty, if it applies, can all affect how much cash you need before you buy.
Learn more: Loan-to-value explained
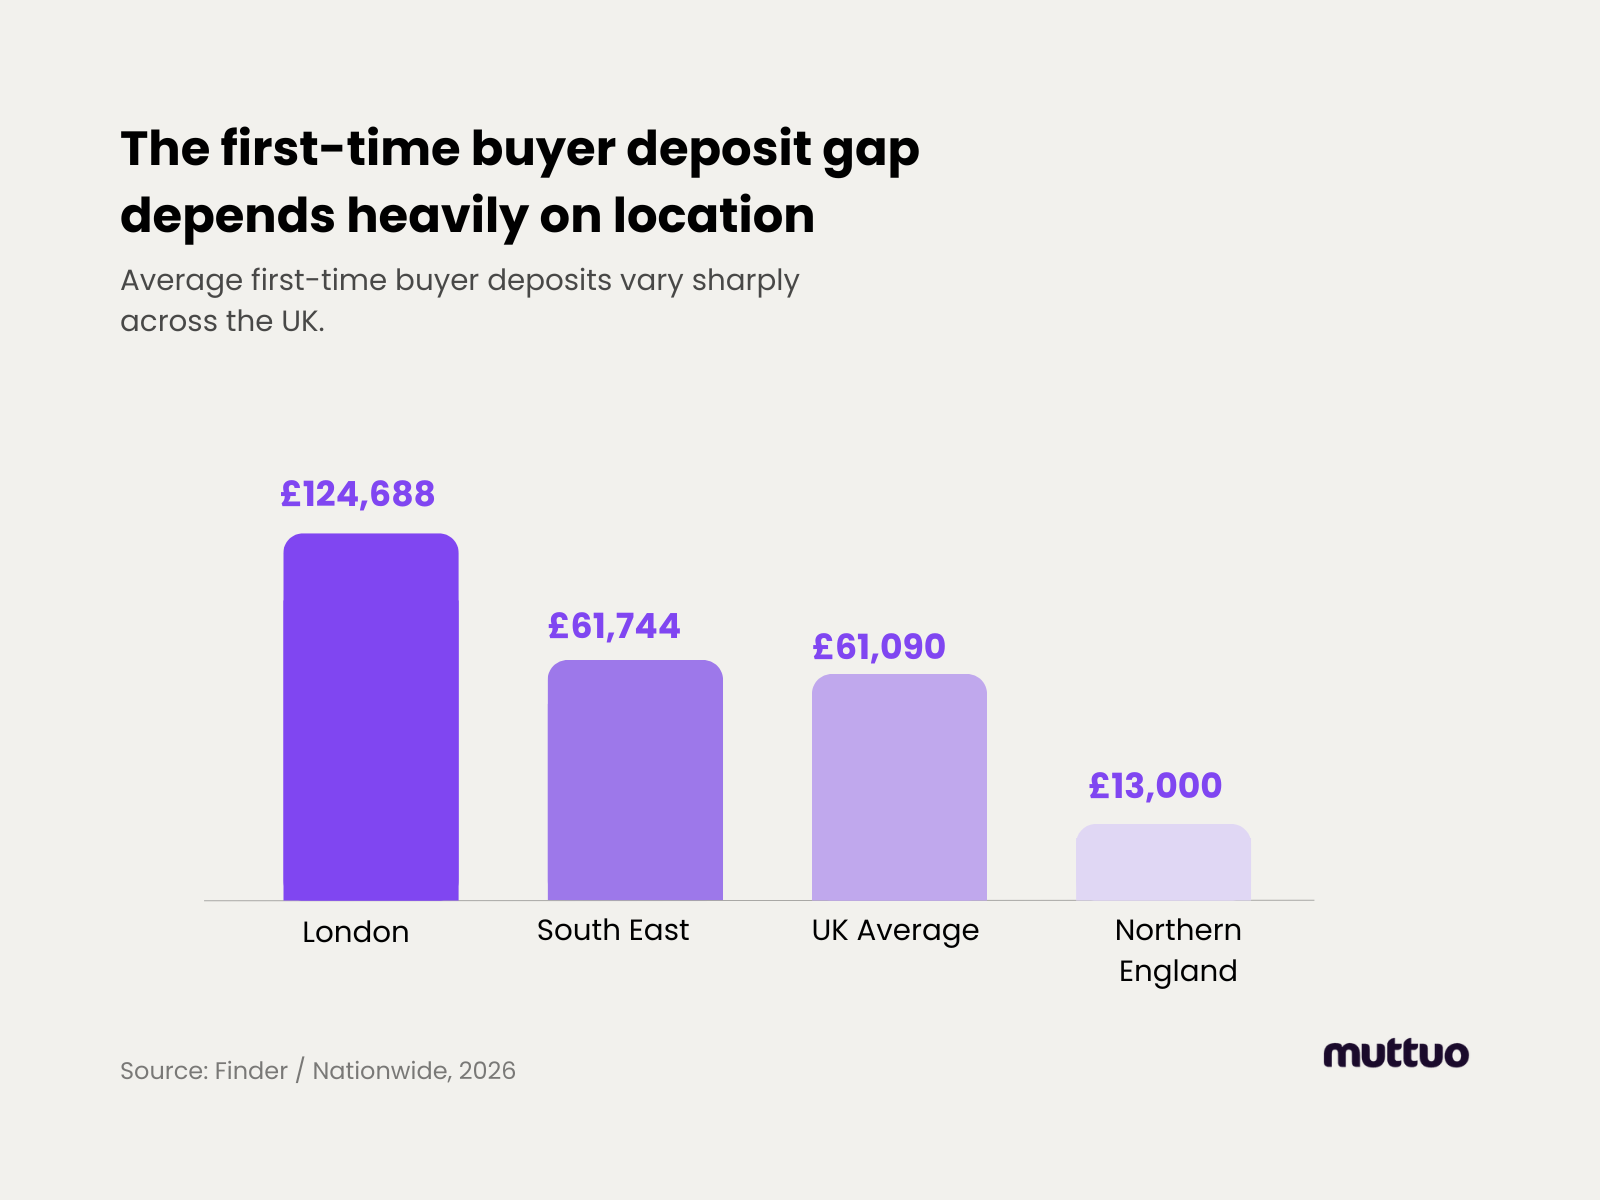
First-time buyer mortgage examples
Simple examples can show how deposit size and loan-to-value affect the amount you may need to borrow.
Here is how the numbers could look based on a £250,000 property purchase.
5% deposit
Property price: £250,000
Deposit: £12,500
Mortgage required: £237,500
Loan-to-value: 95%
Estimated monthly payment
~£1,300 per month
Based on a 35-year term at 5.25% interest
5% deposit
Property price: £250,000
Deposit: £25,000
Mortgage required: £225,500
Loan-to-value: 90%
Estimated monthly payment
~£1,230 per month
Based on a 35-year term at 5.25% interest
With a 5% deposit, the buyer needs less cash upfront but borrows more of the property value. This can make buying possible sooner, although lender choice and rates may be more limited at higher loan-to-value levels.
With a 10% deposit, the buyer puts in more upfront and borrows less. This may improve the range of mortgage options available, depending on lender criteria and the wider application.
These examples are simplified. Your actual options will depend on your income, spending, credit profile, property type, mortgage rate, term, fees and lender criteria.
Ways to buy with a smaller deposit
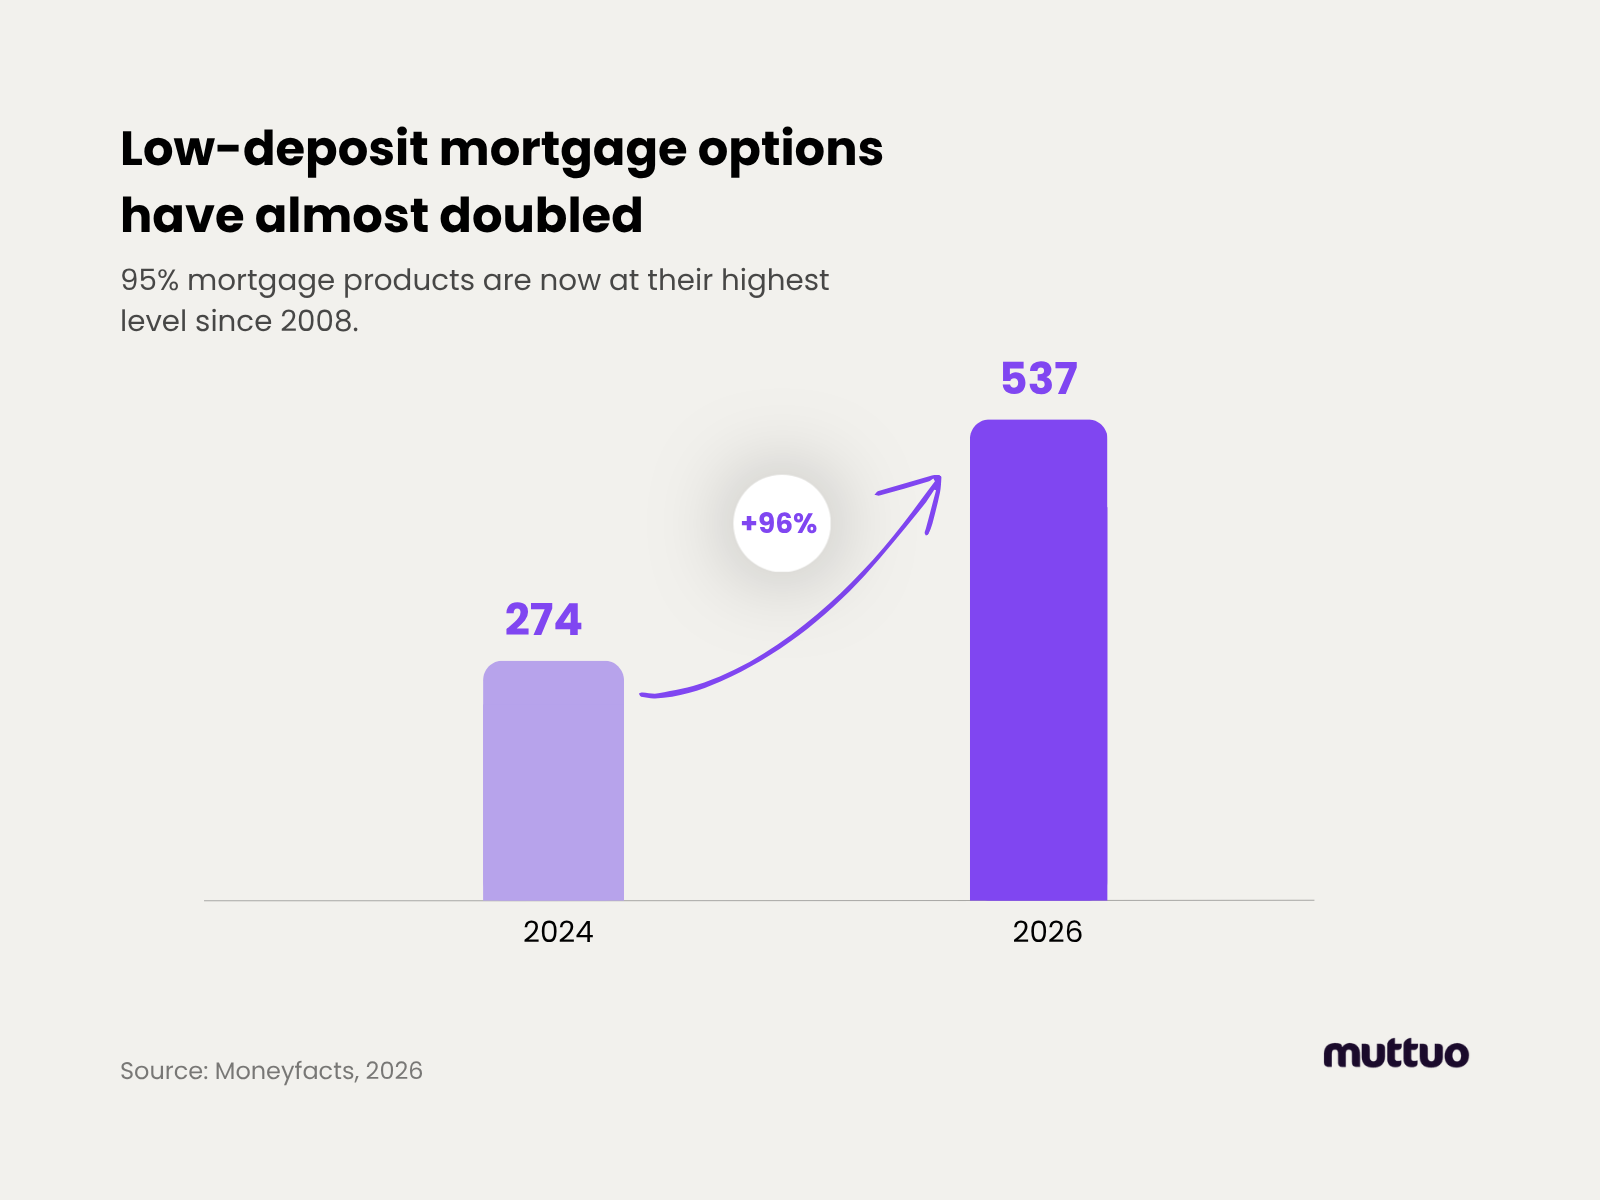
Saving a deposit can be one of the biggest challenges for first-time buyers. If a 10% or 15% deposit feels out of reach, there may still be routes to explore.
Some buyers look at 5% deposit mortgages. Others use family support, such as a gifted deposit or guarantor-style arrangement. Shared Ownership may also reduce the mortgage and deposit needed at the start because you buy a share of the property rather than the full home.
These routes still come with lender rules, affordability checks and long-term considerations. A smaller deposit can help you buy sooner, but it can also mean borrowing more, having less equity and facing stricter lender criteria.
For a fuller breakdown, see our guide to first-time buyer schemes.
What costs do first-time buyers need to budget for?
Your deposit is usually the largest upfront cost, but it is not the only amount you may need before buying your first home.
You may also need to budget for:
- legal fees
- property searches
- survey costs
- moving costs
- mortgage fees
- valuation fees
- buildings insurance
- stamp duty, if it applies
It is easy to focus only on the deposit, especially when you are trying to reach a 5% or 10% target. However, wider buying costs can affect how much you have available for the mortgage deposit itself.
For example, if you have £20,000 saved, not all of that may be available as a deposit. Some of it may need to cover solicitor fees, searches, removals or initial home setup costs.
Before making an offer, it helps to build a full buying budget. That way, you can see what deposit you can realistically use, what costs come with the purchase and how much you may want to keep back as a safety buffer.
Learn more: The costs of buying a home in the UK
First-time buyer stamp duty
Stamp duty can be one of the larger upfront costs when buying a home, although many first-time buyers may pay less because of first-time buyer relief.
In England and Northern Ireland, eligible first-time buyers may pay reduced stamp duty, or none at all, depending on the property price. Scotland and Wales use different property tax systems, so the rules are different there.
First-time buyer relief in England and Northern Ireland
| Purchase price | Stamp duty for eligible first-time buyers |
|---|---|
| Up to £300,000 | £0 |
| £300,001 to £500,000 | 5% on the amount above £300,000 |
| Over £500,000 | First-time buyer relief does not apply |
What first-time buyer relief could save you
| Property price | Standard buyer stamp duty | First-time buyer stamp duty | Potential saving |
|---|---|---|---|
| £300,000 | £5,000 | £0 | £5,000 |
| £400,000 | £10,000 | £5,000 | £5,000 |
| £500,000 | £15,000 | £10,000 | £5,000 |
Figures correct as of 7 May 2026. These examples are for England and Northern Ireland only. Scotland and Wales use different property tax systems, and your solicitor or conveyancer will confirm the final amount.
Stamp duty can affect how much cash you have available for your deposit, legal fees and moving costs. Before you make an offer, it is worth checking whether stamp duty applies and how much you may need to budget.
A stamp duty calculator can give you a useful starting point, but your solicitor or conveyancer will confirm the final amount as part of the purchase process.
Calculate your stamp duty
See how much stamp duty you may need to budget for based on the property price and buyer type.
What lenders check when you apply
Lenders do not only look at your deposit or income. They need to understand whether the mortgage is affordable and whether the property is suitable security for the loan.
They may assess:
- your income and employment type
- your regular spending and debts
- your credit profile and bank statements
- your deposit source
- the property value and property type
- the amount you want to borrow
This means mortgage approval is not based on one factor alone. A strong deposit can help, but the lender still needs to be comfortable with the full application.
For first-time buyers, this can feel like a lot of checks. However, each one has a purpose: to confirm that the mortgage fits your circumstances and that the property meets the lender’s criteria.
Learn more: How lenders decide what you can borrow
Credit checks and first-time buyer mortgages
Your credit profile helps lenders understand how you have managed borrowing in the past.
When you apply for a mortgage, lenders may look at:
- missed payments
- defaults
- credit card balances
- loans
- overdraft use
- recent credit applications
- how long your accounts have been open
You do not always need a perfect credit history to get a mortgage, but credit issues can affect which lenders are available, how much you may be able to borrow and what rate options you can access.
A limited credit history can also matter. If you have never used credit before, some lenders may have less information to assess, which can make the application more detailed.
Before applying, it is worth checking your credit report, correcting any errors and avoiding unnecessary new credit applications. This gives you a clearer idea of what lenders may see before you start the mortgage process.
Mortgage documents checklist
When you apply for a first-time buyer mortgage, the lender will usually ask for documents to support your application.
These documents help confirm who you are, how your income works, where your deposit has come from and whether the mortgage looks affordable.
Common documents may include:
| Document type | What this may include |
|---|---|
| Identity and address | Passport, driving licence or recent proof of address |
| Income evidence | Payslips, P60, employment contract, accounts or tax documents |
| Bank statements | Recent statements showing income, spending and regular commitments |
| Deposit evidence | Savings statements, gifted deposit letter or proof of where the money came from |
| Credit commitments | Details of loans, credit cards, car finance or other regular payments |
The exact documents depend on your income type, deposit source and lender criteria. Preparing them early can help reduce delays once you are ready to apply.
Ready to check your mortgage position?
Muttuo Mortgages can help you review your deposit, documents, credit position and lender options before you apply.
First-time buyer mortgage types
First-time buyers can choose from different mortgage types depending on how they want the mortgage to work.
Some options affect how the loan is repaid, while others affect how the interest rate behaves. For example, a repayment mortgage gradually reduces the balance over time, while a fixed-rate mortgage keeps your interest rate the same for an agreed period.
Common mortgage types include:
| Mortgage type | What it means |
|---|---|
| Repayment mortgage | Your monthly payment usually covers interest and part of the mortgage balance |
| Interest-only mortgage | Your monthly payment covers interest only, so the loan balance must be repaid separately |
| Fixed-rate mortgage | Your interest rate stays the same for a set period |
| Variable-rate mortgage | Your interest rate and monthly payment can change |
| Tracker mortgage | Your rate follows a benchmark, usually above the Bank of England base rate |
The right type depends on your budget, risk tolerance, repayment plan and how much payment certainty you want.
Learn more: Types of mortgages explained
Fixed-rate vs variable-rate mortgages
When choosing your first mortgage, you usually need to decide what type of interest rate suits you.
A fixed-rate mortgage keeps your interest rate the same for an agreed period, such as two, five or ten years. This means your monthly payments stay the same during the fixed period, which can make budgeting easier.
A variable-rate mortgage can move up or down. This means your monthly payments may change if the interest rate changes.
For many first-time buyers, the choice comes down to certainty and flexibility. A fixed rate can make monthly budgeting feel more predictable, while a variable rate may offer more flexibility or the chance to benefit if rates fall.
However, variable payments can also rise. Before choosing, it helps to compare the monthly payment, product fees, early repayment charges, flexibility and how comfortable you would feel if payments changed.
Repayment vs interest-only mortgages
First-time buyers also need to understand how the mortgage will be repaid.
A repayment mortgage means your monthly payment usually covers the interest charged by the lender and part of the original loan. Over time, the mortgage balance should reduce, provided you keep up with payments.
An interest-only mortgage means your monthly payment only covers the interest. The original loan does not reduce during the mortgage term, so you need a separate plan to repay the balance at the end.
For most first-time buyers, repayment mortgages are more common because they are designed to repay the loan by the end of the term.
Interest-only can mean lower monthly payments, but lenders usually apply stricter checks. It is important to understand the long-term responsibility before considering this type of structure.
Longer mortgage terms
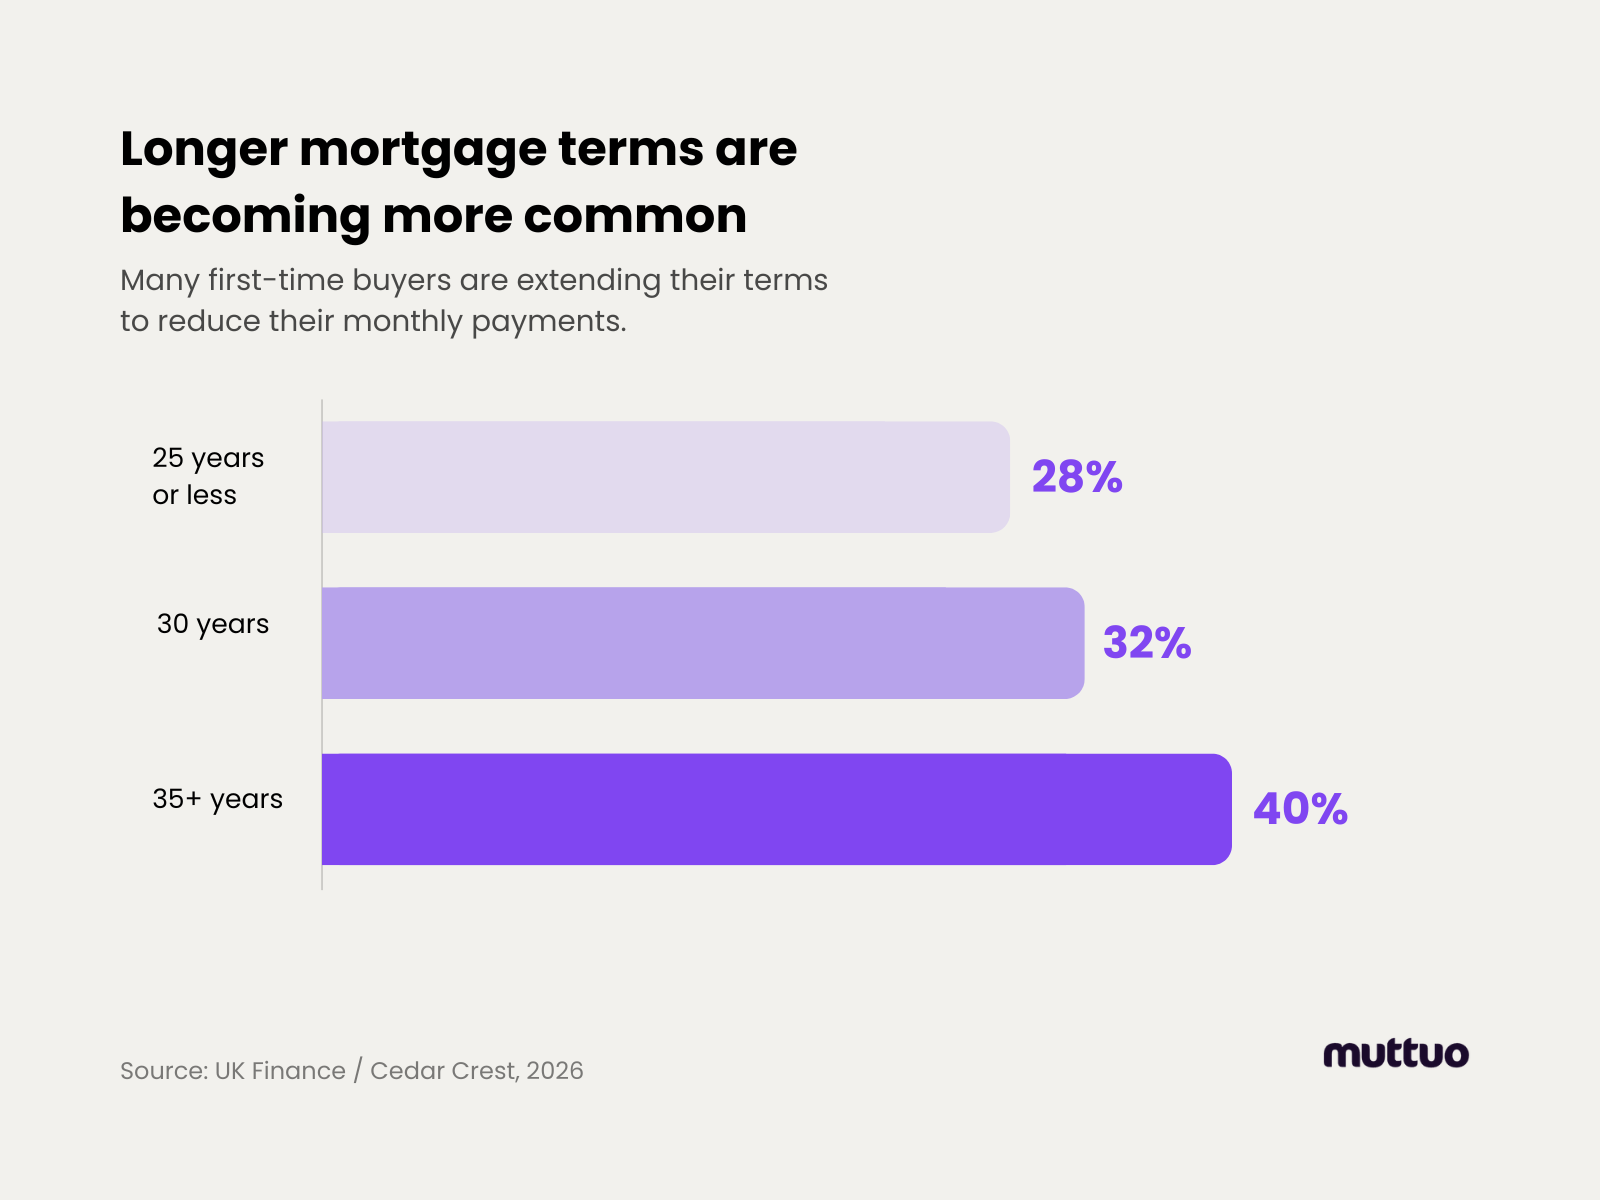
Many first-time buyers choose mortgage terms of 25, 30 or 35 years, depending on their age, affordability and lender criteria.
A longer mortgage term can reduce the monthly payment because the borrowing is spread over more years. This can help with affordability, especially when buying for the first time.
However, a longer term can also mean paying more interest overall. The monthly payment may be lower, but the mortgage lasts for longer, so the total cost can increase.
A shorter term can help you repay the mortgage faster and may reduce the total interest paid. However, the monthly payment will usually be higher.
Before choosing a term, it helps to compare both the monthly payment and the long-term cost. The right term should fit your budget now without creating unnecessary costs over time.
First-time buyer routes and support options
Some first-time buyer options are less about the mortgage type and more about how you buy, who helps you, or what kind of property you choose.
These routes can be useful if you have a smaller deposit, want to buy with someone else, need family support or are considering a new build or Shared Ownership home.
5% deposit mortgages
A 5% deposit mortgage usually means borrowing 95% of the property value and contributing a 5% deposit, subject to lender criteria.
Learn more: 5% deposit mortgages
Gifted deposits
A gifted deposit is money given towards your property deposit, usually by a parent, grandparent or family member, with no expectation of repayment.
Learn more: Gifted deposits
Joint mortgages
A joint mortgage lets two or more people apply for a mortgage together, with each borrower usually responsible for the full mortgage commitment.
Learn more: Joint mortgages
Guarantor mortgages
A guarantor mortgage involves another person supporting the application and potentially becoming responsible if mortgage payments are missed.
Learn more: Guarantor mortgages
Joint borrower sole proprietor mortgages
A joint borrower sole proprietor mortgage lets another person support the mortgage application without being named as a legal owner of the property.
Learn more: joint borrower sole proprietor
Shared Ownership
Shared Ownership lets you buy a share of a property and pay rent on the remaining share, with the option to buy more shares over time.
Learn more: Shared ownership mortgages
New build mortgages
A new build mortgage is used to buy a newly built home or a property still under construction, often with extra lender checks on the build, warranty and completion date.
Learn more: New build mortgages
First home scheme
Under the scheme, eligible buyers may be able to buy a home for 30% to 50% less than its market value. The home must usually be your only or main residence, and local eligibility rules may also apply.
Learn more: First homes scheme
Deposit Unlock
Deposit Unlock was designed to help eligible buyers purchase selected new-build homes with a 5% deposit through participating builders and lenders.
The scheme has now closed to new completions, so it is no longer a standard ongoing option for most new buyers. If you already had a Deposit Unlock mortgage offer in place before closure, the lender may continue to honour it.
Learn more: Deposit Unlock scheme
Lifetime ISA
A Lifetime ISA lets eligible first-time buyers save towards a first home and receive a 25% government bonus, subject to contribution, property price and withdrawal rules.
Learn more: Lifetime ISAs for first-time buyers
Family-assisted mortgages
Family-assisted mortgages use family savings, income or property to support the mortgage application, depending on the product and lender criteria.
Learn more: Family-assisted mortgages
You do not need to work through every option in detail straight away. The aim is to understand which route fits your deposit, monthly budget, lender criteria and long-term plans.
Scheme availability, eligibility and lender rules can change. Before relying on any support route, it is worth checking how it works, whether you qualify and how it affects your mortgage options.
Buying with someone else
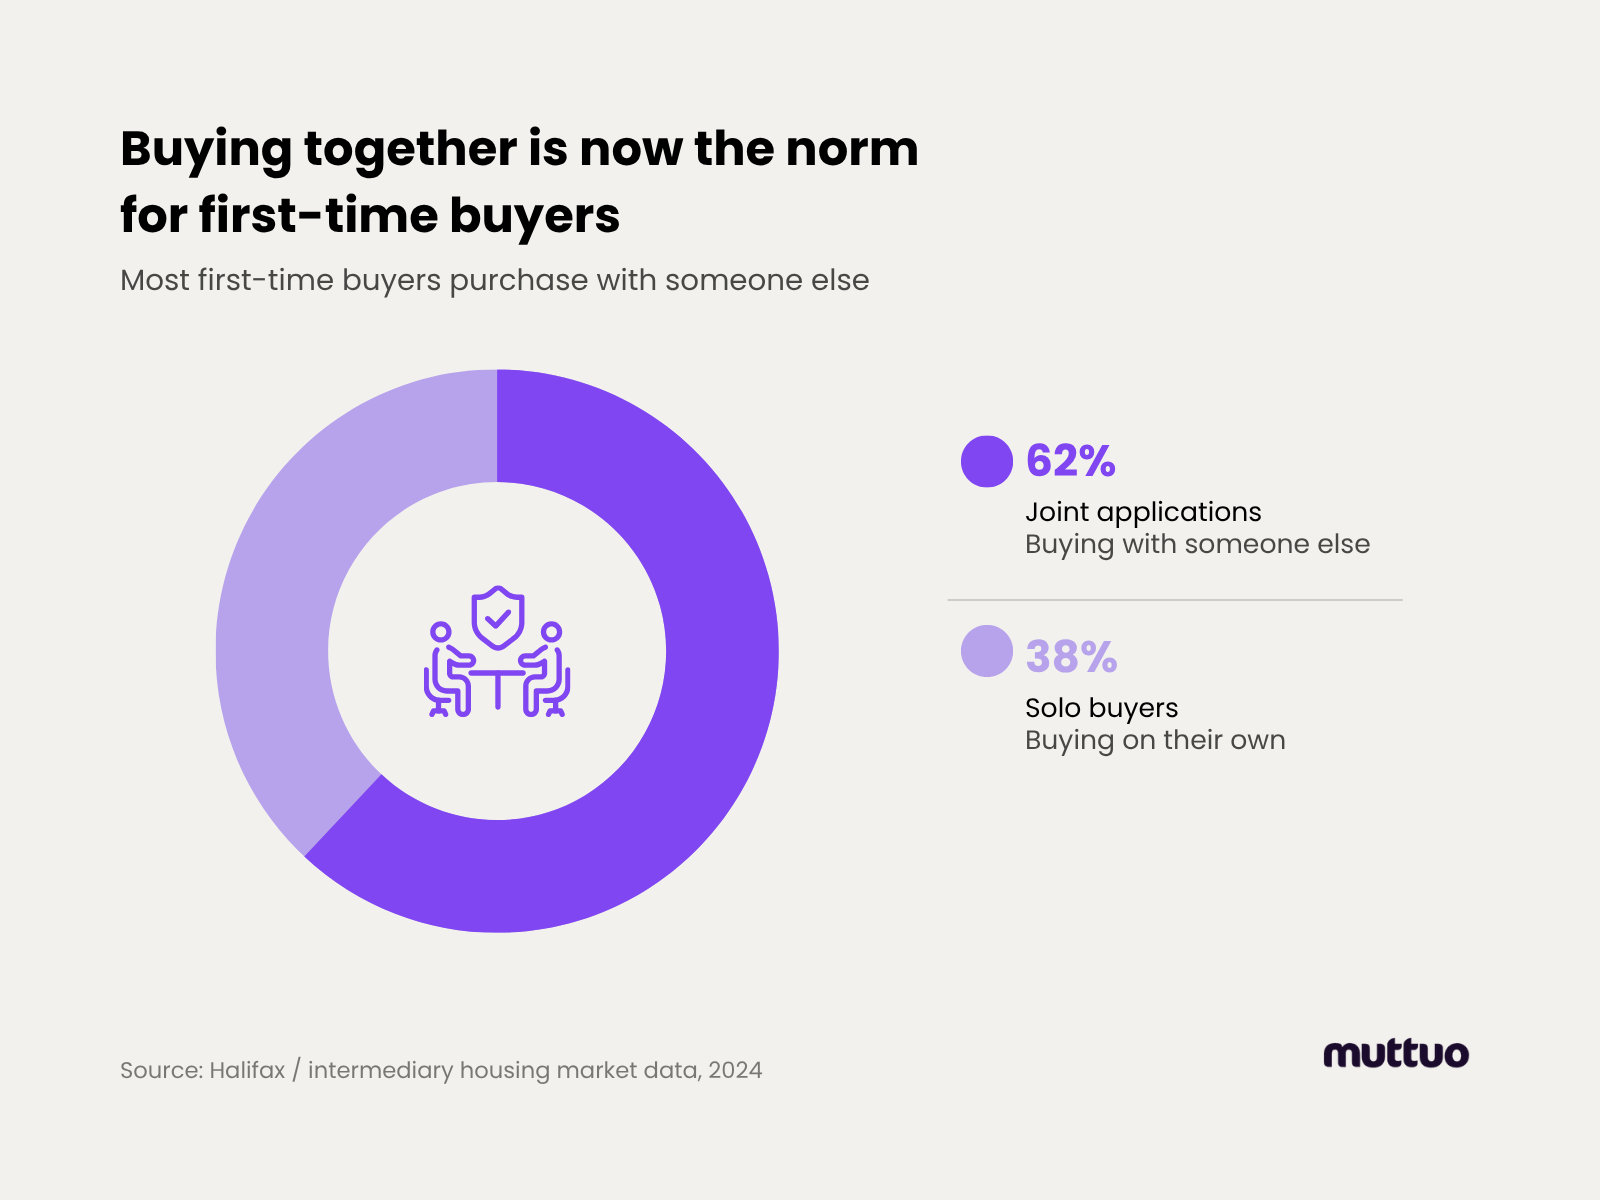
Buying with a partner, friend or family member can make home ownership more achievable, but it also creates a shared financial commitment.
Before applying, it helps to be clear on:
- who is contributing to the deposit
- who will be responsible for the monthly mortgage payments
- whether ownership will be equal or unequal
- how bills, repairs and other property costs will be shared
- what happens if one person wants to sell, move out or be removed from the mortgage later
These conversations can feel awkward, but they are much easier to have before you apply. A solicitor can also help record the ownership arrangement clearly, especially if one person is contributing more than the other.
Family support
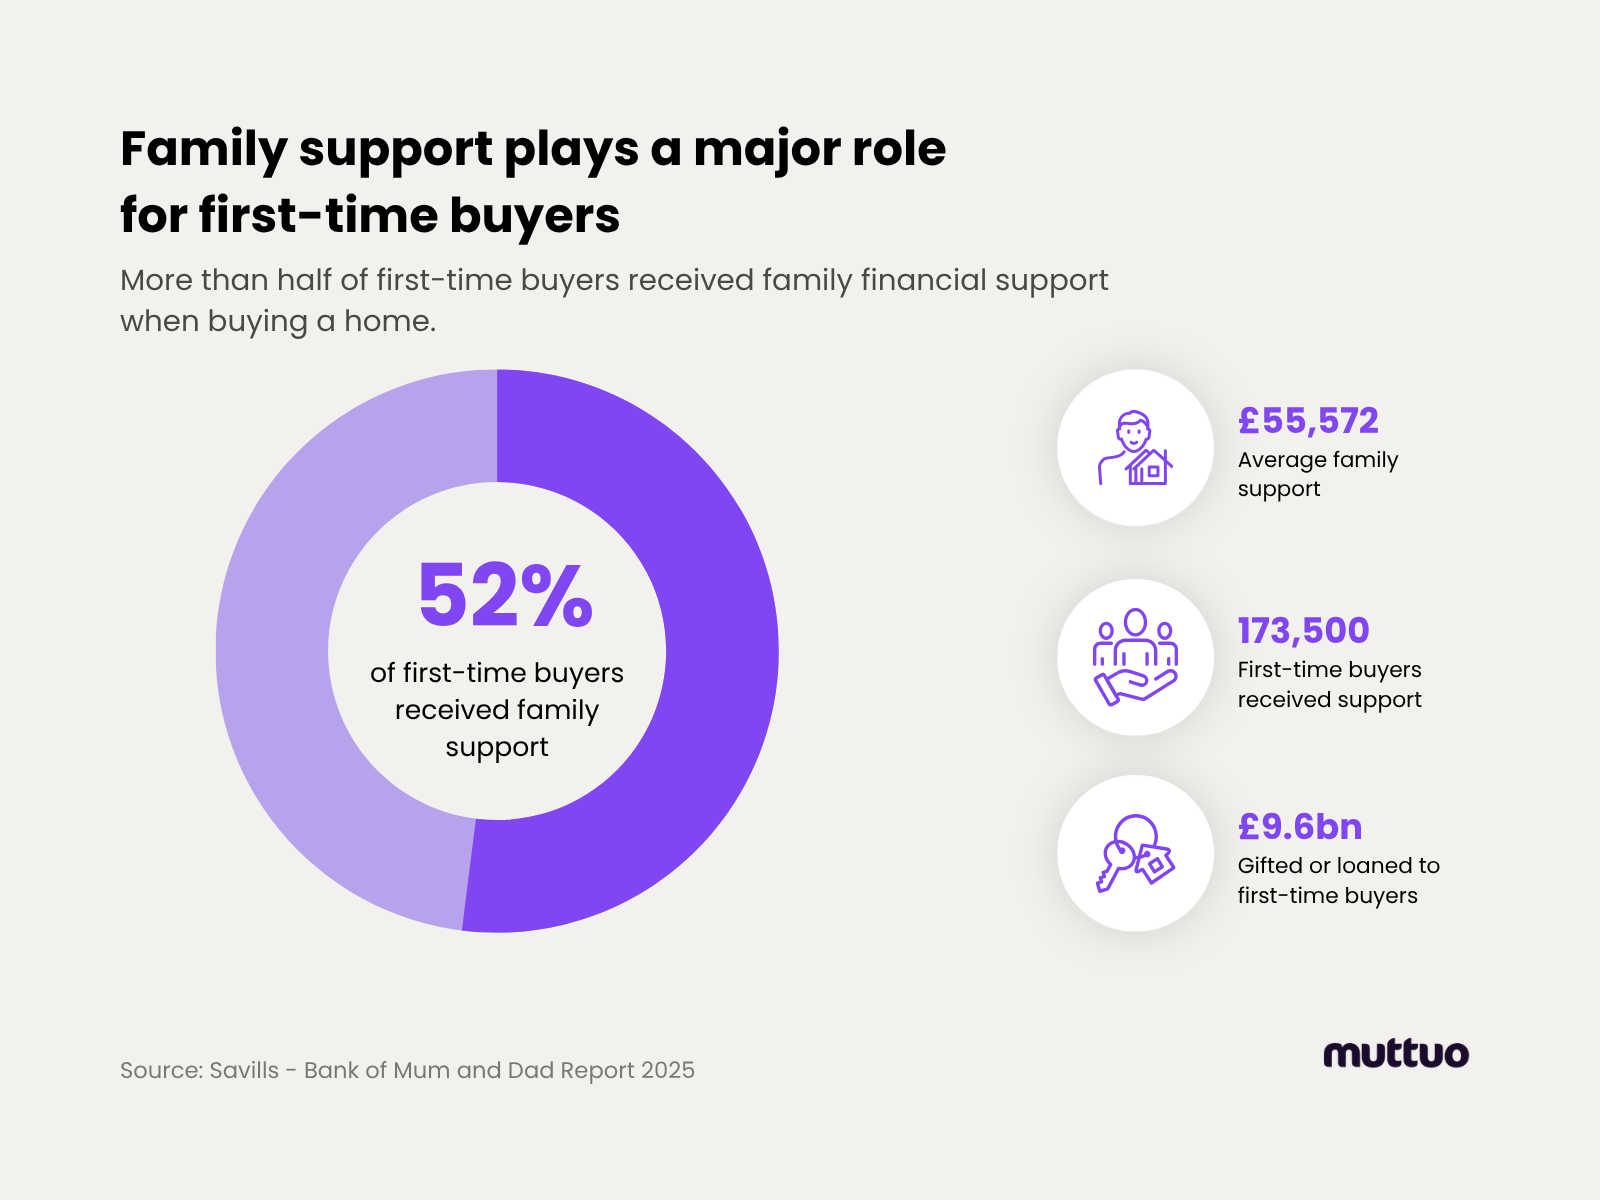
Family support can help some first-time buyers move sooner, especially where deposit savings or affordability are a challenge. However, the type of support needs to be clear before you apply.
Before applying, it helps to understand:
- whether the support is a gift, loan or formal mortgage arrangement
- whether the money needs to be repaid
- whether the family member expects any ownership rights
- whether they will be named on the mortgage or property title
- what evidence the lender may need, such as a gifted deposit letter or proof of funds
Lenders and solicitors may need clear evidence of how the support works. This is especially important if the money is being gifted, because most lenders will want confirmation that it is not a loan and does not give the family member a legal interest in the property.
Shared Ownership
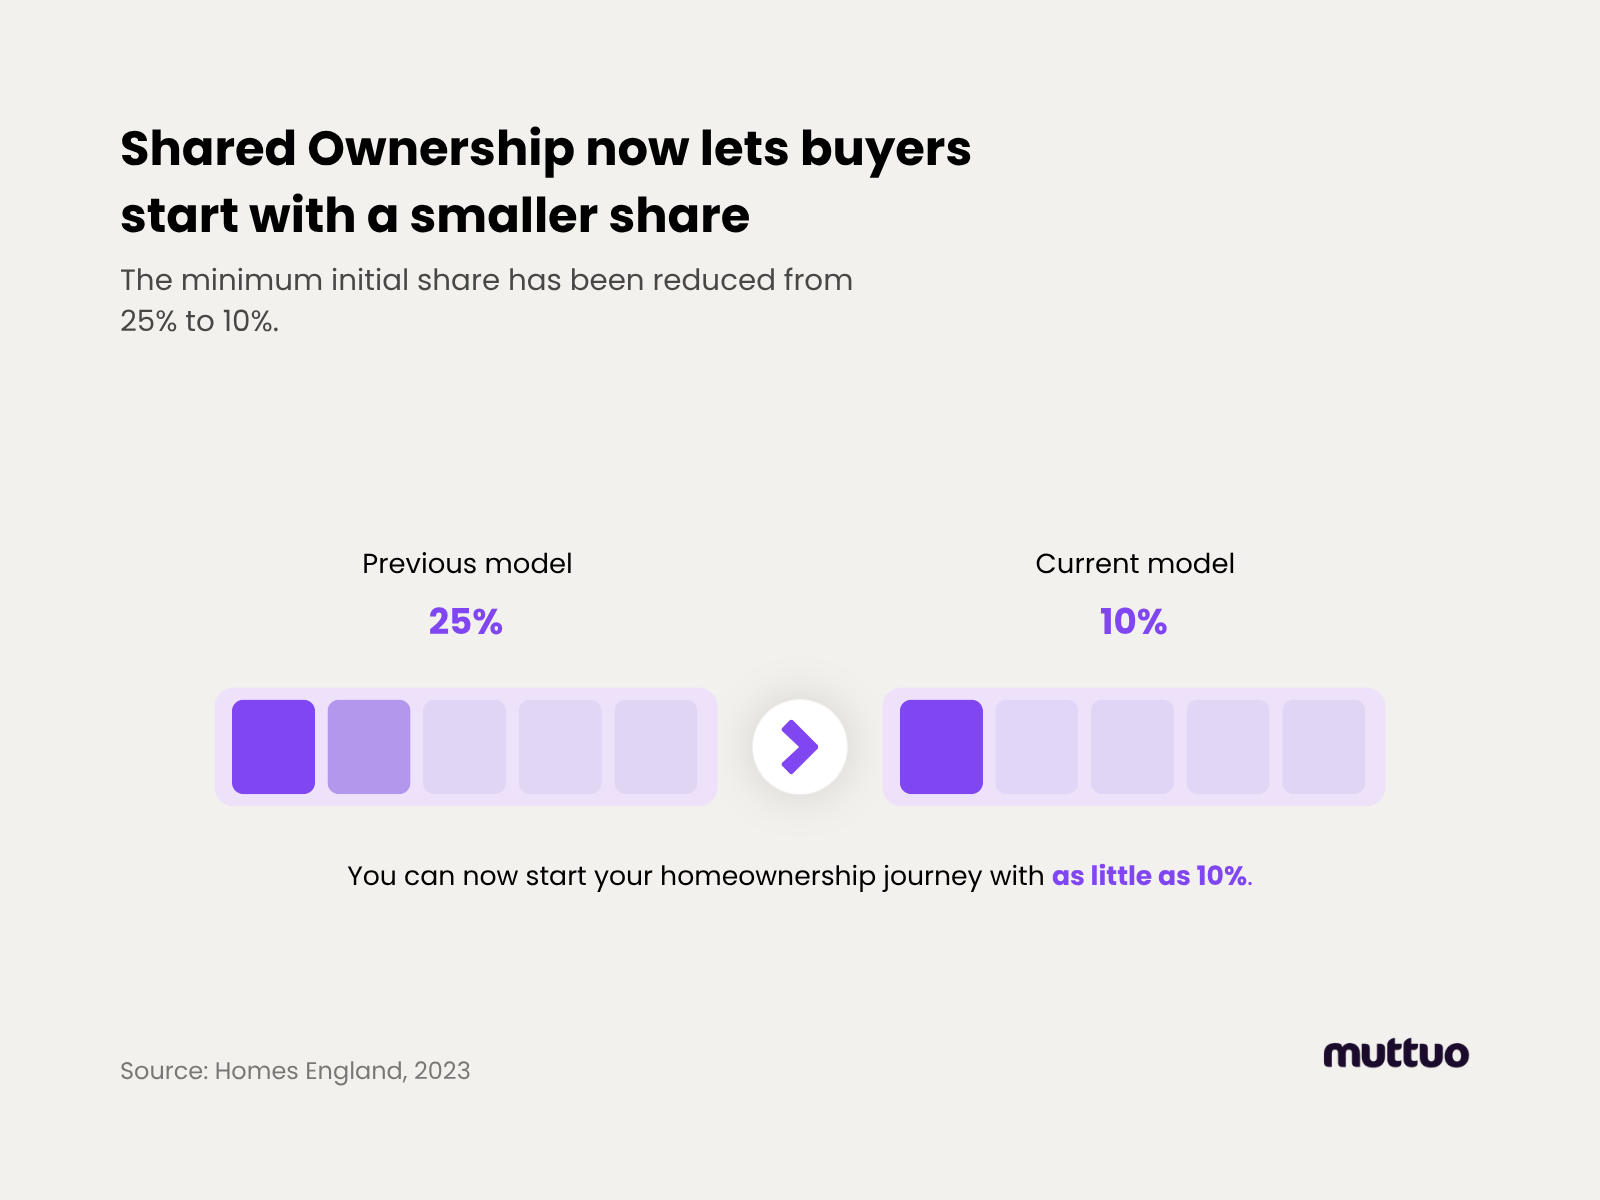
Shared Ownership can help some first-time buyers get onto the property ladder with a smaller upfront deposit than buying a home outright.
Instead of buying the whole property at the start, you buy a share of the home with a mortgage and a deposit. You then pay rent on the share you do not own. Because your deposit is usually based on the share you buy, the initial amount needed can be lower.
Over time, you may be able to increase your ownership through staircasing. As your share rises, the rent on the remaining part of the property usually reduces.
However, Shared Ownership is not only about lowering your deposit. You also need to factor in the combined monthly cost of your mortgage, rent, service charges and other buying costs. Most Shared Ownership homes are leasehold too, so it is important to check the lease terms, restrictions and future costs before you commit.
New build developer incentives
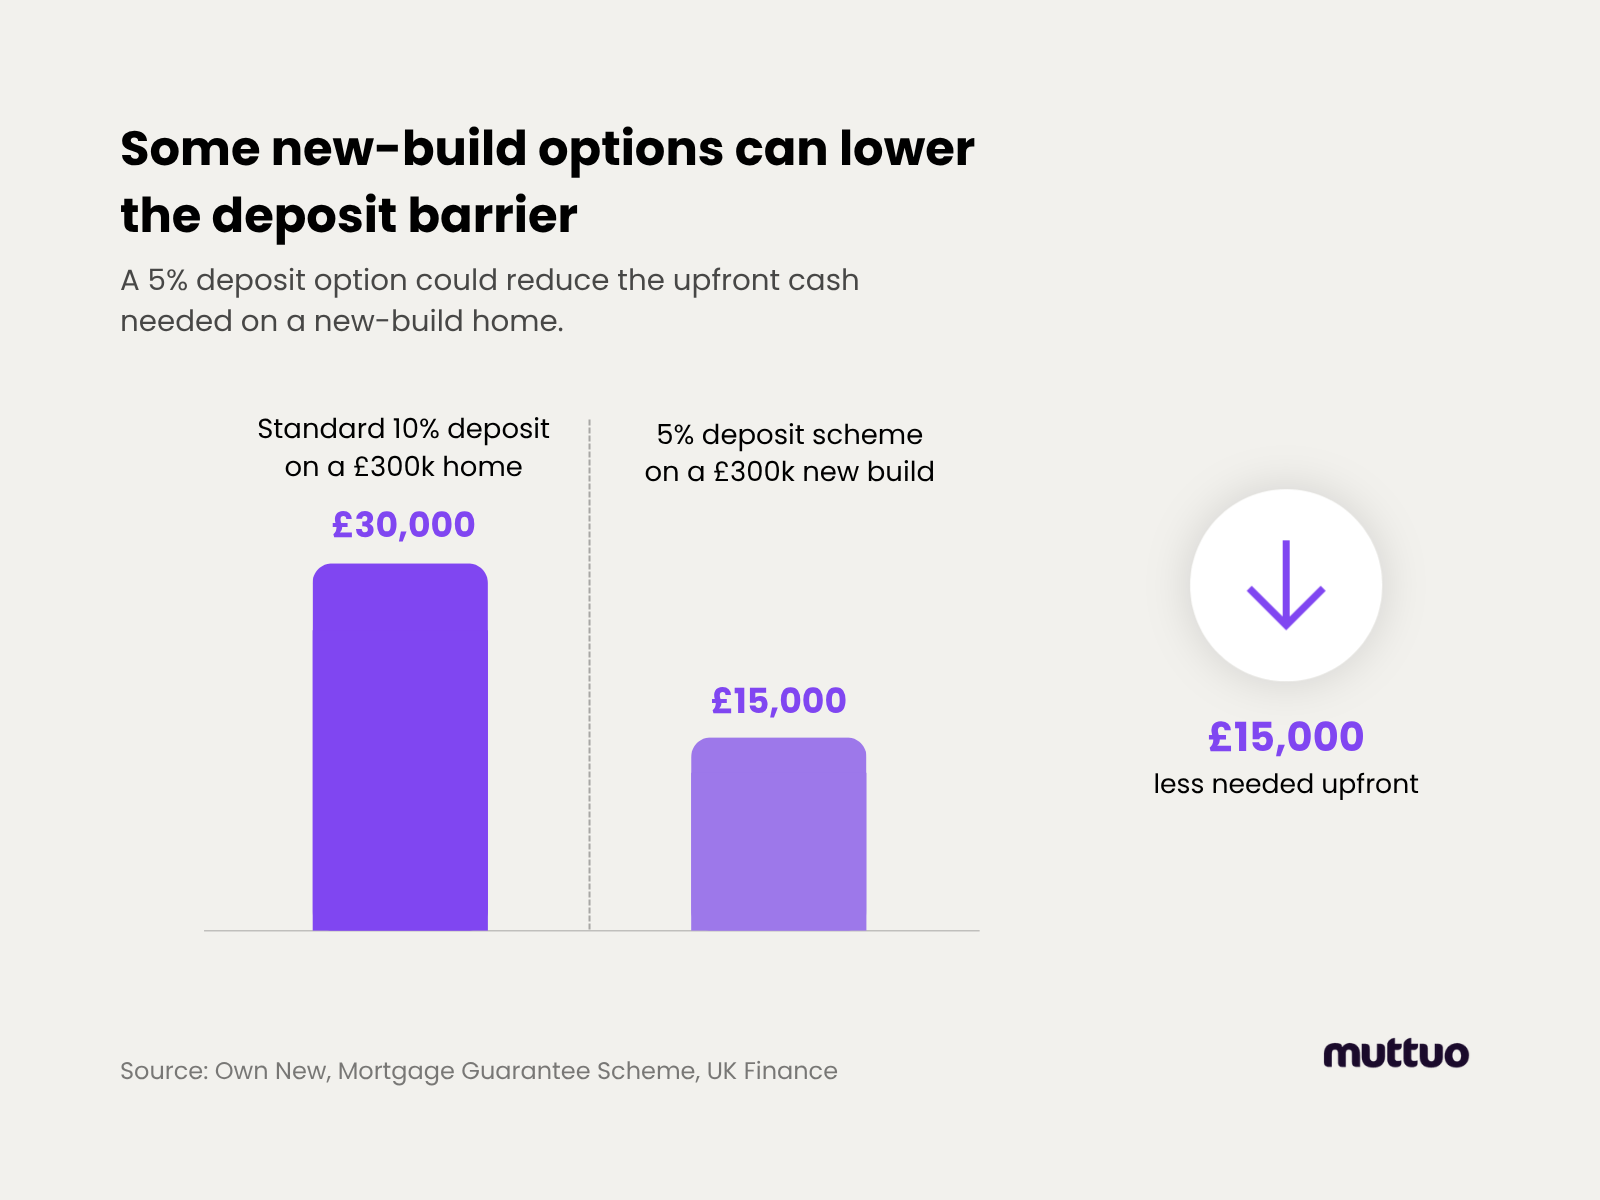
Some new build developers offer incentives to make buying feel more affordable or to help reduce upfront costs.
These incentives can include cashback, upgraded fixtures and fittings, legal fee contributions, stamp duty contributions or deposit support. They can be useful, but they still need to work with the mortgage lender’s rules.
Lenders usually need to know about any developer incentives before they issue a mortgage offer. This is because incentives can affect how the lender values the property, how much deposit you are really contributing and whether the mortgage still meets their criteria.
For example, a developer may offer £5,000 towards legal fees or upgrades. That may help with your buying costs, but the lender may still assess the mortgage based on the property value, your deposit, affordability and the incentive being disclosed correctly.
Before reserving a new build home, it is worth checking:
- whether the incentive is written clearly in the reservation paperwork
- what incentive is being offered
- whether it is cash, upgrades, fees support or deposit support
- whether the lender accepts that type of incentive
- whether it affects the valuation or mortgage offer
Developer incentives can be helpful, but they should not be the only reason you choose a property. It is still important to compare the purchase price, mortgage rate, monthly payment, service charges, warranty, completion date and long-term affordability.
Freehold vs leasehold basics
The type of property you buy can affect your mortgage options, legal checks and long-term costs.
With a freehold property, you usually own the building and the land it sits on. This is more common with houses, although not every house is freehold.
With a leasehold property, you own the right to live in the property for the length of the lease. This is more common with flats, where you may also pay service charges, ground rent or estate charges.
Lenders will usually look at the property type as part of the mortgage application. If the lease is short, service charges are high, ground rent terms are unusual, or the building has specific issues, this can affect which lenders are available.
Before making an offer, it helps to understand whether the property is freehold or leasehold, what ongoing costs apply and whether anything in the lease could affect your mortgage options.
Learn more: Freehold-vs-leasehold: what is the difference when buying a home?
Getting an Agreement in Principle
An Agreement in Principle, often shortened to AiP, gives an early indication of how much a lender may be willing to lend.
It is not a guaranteed mortgage offer. However, it can be useful before you start viewing homes or making offers because it shows that a lender has carried out an initial assessment.
An Agreement in Principle usually looks at your income, deposit, spending, credit profile and the amount you want to borrow. Some lenders use a soft credit check, while others may use a hard credit check, so it is worth checking before applying.
For first-time buyers, an AiP can help turn a rough budget into a clearer buying range. It can also help estate agents and sellers see that you are taking the purchase seriously.
Once you have an Agreement in Principle, you still need to submit a full mortgage application after you find a property. The lender will then assess the details in more depth before deciding whether to issue a formal mortgage offer.
Learn more: Agreement in principle explained
How the mortgage application process works
Once you have found a property and had an offer accepted, you can move from an early borrowing estimate to a full mortgage application.
The lender will review your income, deposit, spending, credit profile and property details in more depth. They may also ask for documents such as payslips, bank statements, proof of deposit, ID and information about any financial commitments.
The process usually includes:
- submitting your full mortgage application
- providing documents and deposit evidence
- the lender assessing affordability and credit history
- a property valuation
- legal checks through your solicitor or conveyancer
- a formal mortgage offer if the lender is satisfied
The property will usually need a valuation before the lender confirms whether they are happy to offer the mortgage. This is for the lender’s benefit and is different from a full survey.
If the lender is satisfied with your application and the valuation, they will issue a formal mortgage offer. Your solicitor or conveyancer can then continue the legal work towards exchange and completion.
The process can feel detailed, but each stage has a clear purpose: to check that the mortgage is affordable, the property is suitable, and the application meets the lender’s criteria.
Learn more: What lenders look for in a mortgage application
What happens after your offer is accepted?
Once your offer is accepted, the purchase moves into a more detailed stage.
You will usually need to submit your full mortgage application, instruct a solicitor or conveyancer and decide whether to arrange a property survey. At the same time, the lender will assess your mortgage application while your solicitor handles the legal checks.
Several things can happen at once. The lender may arrange a valuation, your solicitor may order searches, and the seller’s solicitor may send contract documents.
If everything is satisfactory, the lender can issue your formal mortgage offer. Your solicitor will then continue working towards exchange of contracts and completion.
This is where preparation can make a real difference. Having your documents ready, responding quickly to questions and keeping in touch with your broker, solicitor and estate agent can help the process move more smoothly.
Learn more: First-time buyer mortgage timeline: what happens at each stage
How long does a first-time buyer’s mortgage application take?
Timescales can vary depending on the lender, property, solicitor and how quickly documents are provided.
An Agreement in Principle can often be arranged quickly, but the full mortgage application usually takes longer because the lender needs to assess your documents, affordability and the property.
Some applications move smoothly, especially if the case is straightforward and everything is ready. Others can take longer if the lender asks for more evidence, the valuation raises questions or the legal work is delayed.
Common causes of delays include:
- missing documents
- unclear income evidence
- gifted deposit checks
- property valuation issues
- leasehold enquiries
- slow responses in the chain
Before applying, it helps to prepare your documents early and stay close to your broker, solicitor and estate agent. That way, you can respond quickly if anything needs clarification.
Learn more: How the mortgage process works
Common first-time buyer mistakes to avoid
Buying your first home involves a lot of moving parts, so it is easy to focus on one number and miss the wider picture.
Looking only at maximum borrowing
A lender may approve a certain loan size, but that does not always mean the monthly payment will feel comfortable alongside bills, insurance, repairs and everyday spending.
Focusing only on the deposit
Your deposit is important, but it is not the only upfront cost. You also need to budget for legal fees, surveys, moving costs, mortgage fees and stamp duty if it applies.
Applying before checking your credit report
Some buyers apply before checking their credit report, preparing deposit evidence or understanding how their income will be assessed. This can lead to delays or fewer lender options.
Choosing before comparing the full picture
Before making an offer, it helps to check the full cost of buying, compare mortgage options carefully and understand what the lender will need from you.
A clearer plan at the start can make the rest of the process feel much more manageable.
Mortgage protection and insurance
Once you buy your first home, it is worth thinking about how you would keep the mortgage affordable if your circumstances changed.
Some protection options are designed to help if you die, become seriously ill or cannot work because of illness or injury.
These can include:
- life insurance
- critical illness cover
- income protection
You will usually also need buildings insurance when buying a property with a mortgage. This protects the structure of the home and is normally required by the lender before completion.
Protection is separate from getting approved for a mortgage, but it can be an important part of planning responsibly. The right cover depends on your income, debts, dependants, savings and how you would manage if your household income changed.
Before completing your purchase, it helps to review what cover you already have and whether you need extra protection once the mortgage starts.
Is now a good time to buy your first home?
There is rarely a perfect time to buy your first home. Mortgage rates, house prices, rent, deposit savings and personal circumstances can all move in different directions.
Instead of trying to time the market perfectly, it usually helps to focus on whether buying is realistic and sustainable for you.
That means looking at your deposit, monthly payments, income stability and how long you expect to stay in the property. If the numbers feel manageable and the move fits your plans, buying may be worth exploring.
It is also worth comparing the cost of buying with the cost of renting. However, home ownership also comes with extra responsibilities, such as repairs, insurance and ongoing maintenance.
The right time to buy is not only about the market. It is about whether the property, mortgage and monthly commitment fit your life now and your plans for the next few years.
How Muttuo Mortgages can help first-time buyers
Buying your first home can feel like a lot to manage, especially when you are comparing deposits, lender criteria, affordability checks, mortgage rates and property costs for the first time.
Muttuo Mortgages can help you understand what you may be able to borrow, compare suitable mortgage options and check which lenders may fit your circumstances.
This can be especially useful if your situation is not completely straightforward. For example, you may be buying with a smaller deposit, using a gifted deposit, applying with someone else, considering Shared Ownership, looking at a new build home or unsure how lenders may assess your income.
The aim is to help you move from rough estimates to a clearer mortgage plan, so you know what to prepare, what options may be available and what happens next.
Ready to buy your first home?
Muttuo Mortgages works with over 100 lenders to help you explore suitable deals and find an option that fits your circumstances.
Rated Excellent
by UK homeowners
Frequently asked questions about first-time buyer mortgages
What is a first-time buyer mortgage?
It is a mortgage used to buy your first home.
A first-time buyer mortgage is usually a residential mortgage for someone buying their first home. It is not always a separate product, but first-time buyers may have access to certain deposit options, schemes or lender criteria.
How much deposit do I need as a first-time buyer?
Some buyers may be able to buy with a 5% deposit.
Some first-time buyers may be able to buy with a 5% deposit, although a larger deposit can improve lender choice and rate options. You also need to budget for legal fees, surveys, moving costs and stamp duty if it applies.
How much can I borrow for my first home?
It depends on your income, spending, deposit and lender criteria.
Lenders assess your income, regular commitments, debts, credit profile, deposit and property details. A mortgage calculator can give a starting point, but lender criteria decide what may actually be approved.
What is an Agreement in Principle?
It gives an early indication of what a lender may lend.
An Agreement in Principle, or AiP, is an initial borrowing estimate based on your circumstances. It is not a guaranteed mortgage offer, but it can help before viewing homes or making offers.
Can my parents help with my deposit?
Yes, this is often done through a gifted deposit.
Parents or close family members can often gift money towards your deposit. Lenders usually need a gifted deposit letter, proof of funds and confirmation that the money does not need to be repaid.
Can I buy my first home with someone else?
Yes, many first-time buyers apply jointly.
You can apply for a mortgage with a partner, friend, sibling or family member, depending on lender criteria. Everyone named on the mortgage is usually responsible for the repayments.
Do first-time buyers pay stamp duty?
It depends on the property price and where you are buying.
First-time buyer stamp duty rules vary across the UK. England, Northern Ireland, Scotland and Wales each have different property tax rules, so it is important to check the rules for where you are buying.
How long does a first-time buyer’s mortgage take?
Timescales vary depending on the lender, property and legal work.
An Agreement in Principle can often be arranged quickly, but the full mortgage application and legal process take longer. Delays can happen if documents are missing, valuation questions arise, or conveyancing takes longer than expected.
Should I use a mortgage broker as a first-time buyer?
A broker can help compare lenders and explain the process.
A mortgage broker can help you understand what you may be able to borrow, compare suitable mortgage options and prepare your application. This can be useful if you are unsure where to start or if your situation is not straightforward.


