


Co-Ownership in Northern Ireland: how it works
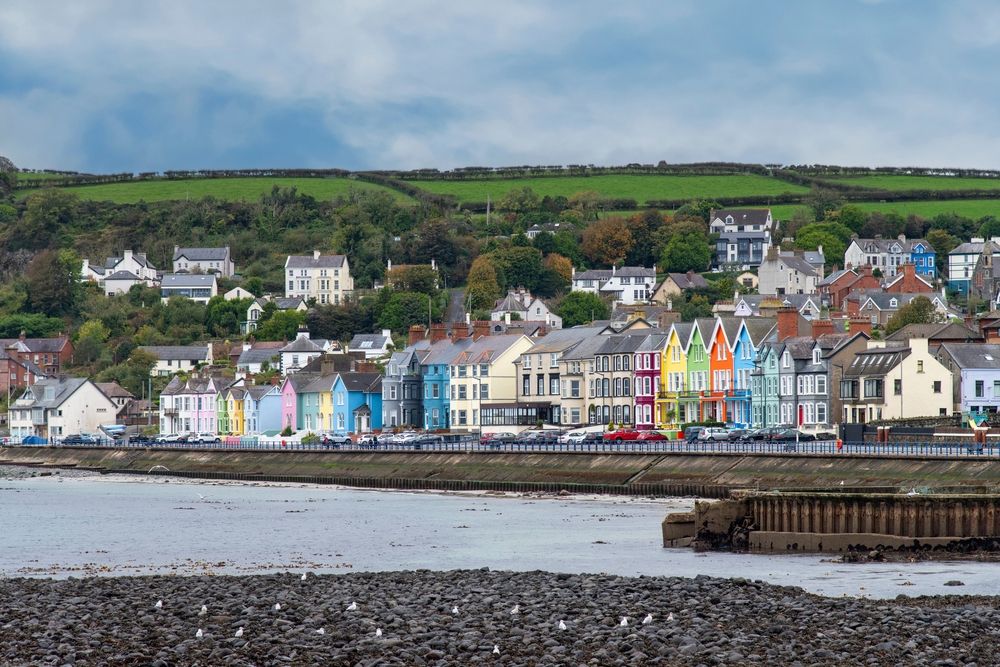
Explore how Co-Ownership works in Northern Ireland, what your mortgage and rent could cost, and how you can buy more of your home over time.
How to improve your mortgage affordability
Learn how lenders assess affordability and which changes to your debts, spending, credit history, deposit and mortgage term may strengthen your application.
How much debt is acceptable for a mortgage in the UK?
Existing debt does not automatically prevent mortgage approval. Learn how lenders assess monthly repayments, credit history and disposable income.
How many times your salary can you borrow for a mortgage?
Your salary is a starting point for understanding what you could borrow. Explore how mortgage lending multiples work and what else shapes your mortgage budget.
How mortgage affordability checks work
Mortgage affordability checks consider your income, spending, debts and credit history. Find out what lenders review and how to prepare.
Joint mortgage with bad credit
Yes, you can get a joint mortgage if one applicant has bad credit. Lenders will assess both applicants, the type of credit issue and your overall affordability before making a decision.
How much can you borrow with a joint mortgage?
A joint mortgage could help you borrow more by combining your incomes, but lenders also look at your spending, deposit and credit history before deciding how much they’ll lend.
5% mortgages: buying with a smaller deposit
A 5% deposit mortgage could help you buy a home sooner. Learn how these deals work, who may qualify and what to check before applying.
Mortgage affordability: what can you comfortably afford?
Understand the difference between your borrowing estimate and a comfortable budget, then find the tools and guidance for your next step.